
1. Introduction
Profit Adjustment Formulas (PAFs) are contractual mechanisms used to vary a contractor’s profit in response to changes in actual costs, productivity, or external economic factors. Their primary purpose is to allocate risk fairly, encourage cost efficiency, and reduce disputes arising from price fluctuations or cost overruns.
These formulas are widely used in:
- Incentive‑based contracts
- Long‑term construction and engineering contracts
- Public‑sector procurement
- Contracts subject to inflation or market volatility
While profit adjustment formulas cannot perfectly mirror real‑world cost movements, they provide a transparent and pre‑agreed method for modifying profit outcomes in a way that is acceptable to both employer and contractor.
For clarity, not every escalation mechanism is a profit adjustment formula in the strict sense. A direct PAF changes the contractor’s profit entitlement by reference to agreed cost-performance metrics. By contrast, a price adjustment mechanism such as CPAP adjusts the contract value through published indices and weightings; it may protect profitability, but it does so indirectly rather than by recalculating the contractor’s actual margin.
2. Purpose of Profit Adjustment Formulas
The key objectives of profit adjustment formulas include:
- Risk sharing between employer and contractor
- Incentivising cost control and efficiency
- Providing predictability in long‑term contracts
- Reducing claims and disputes relating to escalation and overruns
- Maintaining commercial fairness under changing economic conditions
In incentive contracts, profit is deliberately made variable, increasing when performance improves and decreasing when costs exceed agreed targets.
3. Profit Adjustment in Incentive Contracts
3.1 Fixed Price Incentive (Firm Target) Contracts
A common international application of profit adjustment formulas occurs in Fixed Price Incentive (Firm Target) contracts. These contracts establish at the outset:
- A target cost
- A target profit
- A target price
- A price ceiling
- A profit adjustment (sharing) formula
Under this model:
- If actual costs are below target, profit increases
- If actual costs are above target, profit decreases
- Beyond the price ceiling, the contractor bears all additional cost risk
The profit adjustment formula is usually expressed as a sharing ratio, such as 80/20, indicating how cost savings or overruns are shared between employer and contractor. The contract should state expressly which percentage belongs to which party. For example, an 80/20 ratio may mean that the employer takes 80% of a saving and the contractor receives 20%, or the reverse, depending on the drafting convention used.
3.2 Cost-Plus Incentive Fee Contracts
Cost-plus incentive fee contracts reimburse the contractor for allowable costs, but vary the contractor’s fee according to agreed performance or cost outcomes. They are often used where the final scope or cost cannot be defined with enough certainty for a pure fixed-price arrangement, but where the employer still wants to create a measurable incentive for cost discipline.
In this model, the contract usually identifies a target cost, a target fee, and a formula for increasing or reducing the fee depending on whether actual allowable costs are below or above the target. The contractor is protected from bearing all cost risk, but its profit is still exposed to performance against the agreed target.
3.3 Target Cost Contracts
Target cost contracts are commonly used in construction, engineering, and collaborative procurement models. The parties agree a target cost and then share savings or overruns through a pain/gain mechanism. This makes the final commercial outcome dependent on actual cost performance rather than only on the original contract sum.
Where actual costs are lower than the target cost, the saving is shared between employer and contractor in the agreed proportions. Where actual costs exceed the target cost, the overrun is also shared unless the contract provides for a cap, ceiling, or other limit on the employer’s exposure. Target cost arrangements therefore rely heavily on transparent cost records, agreed measurement rules, and clear treatment of variations and disallowed costs.
4. Structure of a Profit Adjustment Formula
A typical profit adjustment formula links profit to cost performance through a mathematical relationship:
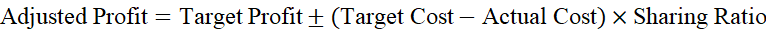
Key components include:
- Target profit agreed at contract inception
- Actual cost determined at completion or measurement dates
- Sharing ratio defining how gains or losses are distributed
This structure ensures that profit varies inversely with cost, creating a measurable incentive for efficiency.
Worked example
Assume a target cost of R10 million, target profit of R1 million, actual cost of R9.6 million, and a sharing ratio under which the contractor receives 20% of any saving against target cost. The saving is R400,000. The contractor’s adjustment is therefore R80,000, calculated as R400,000 × 20%. The adjusted profit is R1.08 million. If actual cost were R10.4 million and the contractor bore 20% of the overrun, the adjusted profit would reduce by R80,000 to R920,000.
5. Profit Adjustment Through Price Escalation Formulae
5.1 South African Construction Practice
In South Africa, profit adjustment is often achieved indirectly through Contract Price Adjustment Provisions (CPAP) rather than explicit profit‑sharing formulas. CPAP applies index‑based escalation to the contract value to reflect changes in:
- Labour costs
- Material prices
- Plant and equipment costs
- Fuel prices
The CPAP system uses published indices, including Statistics South Africa P0151.1 construction material price indices, and applies work group weightings to different cost components. Its objective is to provide an agreed escalation recovery method that reduces disputes and gives reasonable reimbursement for price fluctuations. CPAP adjusts the contract price, not the contractor’s actual profit margin; however, the adjustment may preserve the commercial margin by reducing the effect of inflation or input-cost movement on the contractor’s net outcome.
6. Limitations of Profit Adjustment Formulas
Despite their advantages, profit adjustment formulas have inherent limitations:
- They cannot precisely reflect actual costs incurred on a project
- Indices may lag behind real market conditions
- Administrative complexity may increase
- Over‑reliance on formulas can discourage commercial negotiation
Industry guidance consistently warns that formulas should be viewed as approximation tools, not exact reimbursement mechanisms.
7. Relationship with Accounting Treatment
Profit adjustment mechanisms interact closely with revenue recognition for long-term contracts. Under current revenue recognition frameworks such as IFRS 15, entities generally assess the transaction price, including variable consideration, and recognise revenue when or as performance obligations are satisfied. Where revenue is recognised over time, expected profit adjustments, incentives, penalties, escalation amounts, and other variable elements should be reflected in updated cost and revenue forecasts to the extent permitted by the applicable accounting standard. This ensures that financial reporting reflects the current best estimate of final contract outcome rather than only the original target margin.
8. Best‑Practice Considerations
When drafting or applying profit adjustment formulas, the following principles are recommended:
- Clearly define target cost, profit, and ceilings
- Use objective and published indices where escalation applies
- Avoid excessive complexity
- Align incentives with project objectives
- Ensure transparency and auditability
- State the base date or base month for any index-linked adjustment
- Identify excluded costs, provisional sums, contingencies, taxes, and items not subject to adjustment
- Explain how variations, delays, extensions of time, and acceleration affect the adjustment calculation
- Consider whether caps, floors, collars, or price ceilings are required to limit extreme outcomes
- Include audit rights, supporting records, and calculation procedures so that adjustments can be verified
- Provide a fallback method if a published index is discontinued, rebased, delayed, or materially changed
Well‑designed formulas promote collaboration rather than adversarial behaviour.
9. Conclusion
Profit Adjustment Formulas play a vital role in modern contracting by balancing risk, incentivising efficiency, and preserving fairness under uncertain economic conditions. Whether implemented directly through incentive contracts or indirectly through price adjustment mechanisms such as CPAP, they remain an essential tool in long‑term and high‑value projects.
Their effectiveness ultimately depends on clear drafting, realistic targets, and mutual trust between contracting parties.
Disclaimer
This information is provided for general guidance only and does not constitute professional advice. While care has been taken to ensure accuracy, no responsibility is accepted for errors, omissions, or for any outcomes resulting from the use of this information. Users should apply their own professional judgement and seek appropriate advice where necessary.